The most common path to homeownership for borrowers with solid credit and a down payment ready.
Have mortgage questions? We’re here to help you fetch answers.
Call or Text
(530) 922-2479

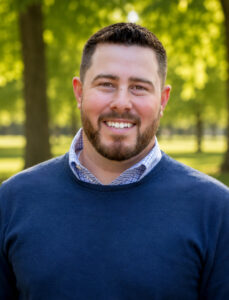
Loan Officer
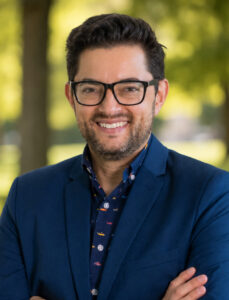
Loan Officer
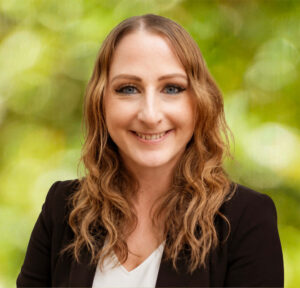
Loan Officer
Loan Officer
Loan Officer
Loan Officer
Loan Officer
Loan Officer
Loan Officer
Loan Officer
Loan Officer
Loan Officer
Loan Officer
Loan Officer
HD Pro Sales Manager, Loan Officer
Loan Officer
Loan Officer
Beyond the numbers, what truly drives me is serving my clients. I'm blessed to be one of the highest-rated loan officers in our area, with a 4.95 review rating across 350 experiences – a testament to the trust my clients place in me.
Loan Officer
Whether you’re planning to buy in a few months, a few years, or just wondering if homeownership is even in the cards, I’m happy to help you build a plan without any pressure.
Loan Officer
Buying a home is one of the most significant milestones in a person’s life, and the journey is often as emotional as it is financial. My path into the mortgage industry was inspired by my own experience purchasing my very first home. During that process, I found that I connected far more with my Mortgage Loan Officer than anyone else involved. That deep level of guidance, communication, and trust left a lasting impression on me and ultimately inspired me to become an MLO myself.
Loan Officer
I bring more than 20 years of experience serving others as an emergency room nurse to my role as a loan officer with Happy Dog Home Loans. Born and raised in Walnut Creek, California, I built my career around helping people through important moments with compassion, patience, and confidence.
Loan Officer
Born in Mt. Shasta and raised in Northern California, Jason Pezzetti brings a wealth of local knowledge and passion to his role in the mortgage industry. A Chico State graduate, Jason has been helping clients navigate the home-buying process for 8 years. Before his career in mortgages, Jason was a teacher, and his love for education continues as he enjoys explaining the many mortgage programs available to help clients achieve their financial goals.
Loan Officer
I’m a mortgage loan officer with Happy Dog Home Loans, and I’ve been helping homebuyers and homeowners in Chico, Butte County and across Northern California for nearly 10 years. I’m licensed in both California and Oregon, and I specialize in move-up buyers, first-time homebuyer programs and specialty home loans that other lenders often find hard to close.
Loan Officer
I believe buying a home should feel exciting, not overwhelming. My goal is to make the mortgage process as clear and straightforward as possible by taking the time to understand your goals, answer your questions, and help you feel confident every step of the way.
Loan Officer
I started my career in the mortgage industry in 2010, and I’ve gained the experience needed to help you find the right home loan that fits your financial goals. I specialize in helping individuals and families navigate the home buying process from start to finish with confidence and clarity. Whether you’re a first-time homebuyer, an investor, or refinancing your current home, I’ll be with you every step of the way.
Loan Officer
With over 10 years of experience in the real estate and mortgage industries, I have built my career around helping clients successfully navigate one of the most important financial decisions of their lives—homeownership. My diverse industry background allows me to guide clients through the home financing process with confidence and expertise. I earned my BS in Business Administration with a concentration in Real Estate Development from Arizona State University, providing a strong foundation in both the financial and real estate sectors.
Loan Officer
Justin Bowman has been helping people finance their homes since 2003. With more than 20 years in lending, he's guided clients through every kind of market. Today he's a loan officer with Happy Dog Home Loans in Chico, California. As a mortgage broker, Justin isn't tied to one bank's rates or rules. He shops more than 100 lenders to find the loan program, rate, and terms that actually fit each client's goals.
Loan Officer
Hailing from Paradise, California, Megan Dusell brings a vibrant, free-spirited energy to the mortgage industry. Married with two daughters, Megan enjoys spending time with her family at music festivals and glamping trips along the scenic California coast. An avid music lover, she is known for her love of singing and even whistling, often filling the office with her joyful tunes between conversations with clients.
Loan Officer
Born in Colorado and raised in sunny Southern California, Mike McKee brings a competitive edge and a laid-back vibe to the mortgage industry. A former college golfer and still a scratch player today, Mike is just as comfortable on the golf course as he is working with clients. After graduating from Chico State, he has spent the last 9 years in the mortgage business, helping clients achieve their financial goals.
Loan Officer
Whether structuring a first time buyer loan, a cash-out refinance, or creative financing for an investment property, I focus on clear communication, strategic thinking, and solutions tailored to each client’s goals. My mission is simple: provide the insight and loan products that turn real estate into a vehicle for growth, income, and lifestyle flexibility.
Loan Officer
HD Pro Sales Manager, Loan Officer
With 11 years of experience in the mortgage business, Tori Goble is known for her expertise and love for connecting with people. Before stepping into mortgages, she owned a wine bar in Chico, CA, where her passion for building community and bringing people together truly flourished.
Loan Officer
I’m Vinnie Anderson, a mortgage professional serving Chico, Durham, and the surrounding communities since March 2016. I’m passionate about helping people navigate home financing with clear communication, personal attention, and guidance they can trust. Whether you’re buying your first home, making your next move, or refinancing, my goal is to make the process straightforward and help you find financing that fits your goals.
A conventional loan is a mortgage that is not backed by a government agency. It typically requires a credit score of 620 or higher and a down payment as low as 3%. Conventional loans offer competitive rates and flexible terms, and are the most common path to homeownership for borrowers with solid credit and stable income.
We’ll review your credit profile, down payment, income, and home price so you can see whether a conventional loan gives you flexibility, competitive pricing, and a path that makes sense for your goals.
We'll look at credit, income, debt, and down payment so you know whether a conventional loan is the right fit.
From 30-year to 15-year options, we'll compare payment structure, rates, and long-term cost.
We'll show when PMI applies, how much it may cost, and when you can expect it to end.
We'll compare interest rate, loan term, fees, and monthly payment so you can decide with confidence.
People consistently say the same things: it finally felt straightforward, they understood their options, and they weren’t treated like a number.
Just completed our refinance and it was a breeze! Megan and Jacquie are an amazing team! They are smart, hardworking, caring and knowledgeable!…
Olga G.
I had a truly wonderful experience working with HappyDog. From the very beginning, the team was professional, helpful, and prompt in guiding me through…
Jenny U.
If I could give Marci and Tori 10 stars I would! They were so friendly and easy to talk to. You can tell they enjoy helping people and that’s what makes them so good at their job!
RyAnn G.
Mike McKee, excellent service. His patience helped me to walk through the homebuying process with ease. He was available whenever I contacted him…
Althea O.
Great experience overall! Jason always kept us up to date and communicated regularly and is very good about replying quickly to questions.
AD A.
OMG!!! Mike Mckee is phenomenal…I worked with him for almost 2yrs..I had lots of issues prior to opening and he continued to reach out to me and stay in contact…
Valerie S.
HappyDog was easy to work with and highly responsive during our escrow process. I highly recommend them.
Taylor M.
Mike McKee’s professionalism and efficiency are truly impressive. He seamlessly guides clients through the lending process with his expertise…
Edward K.
Tori was amazing! She was providing several options for our budget for us to review and explained pros and cons with each option…
Rio B.
We can’t say thank you enough to vinnie, Lisa, and the whole team at happydog home loans! They made the whole process simple and straight forward…
Mariah H.
We had an absolutely amazing experience working with Happy Dog Lending while buying our first home! As first-time buyers, we had a lot of questions…
Ursula T.
Great response time, easy formatting and uploading documents. Always kind in our interactions VERY patient…
David B.
Just completed our refinance and it was a breeze! Megan and Jacquie are an amazing team! They are smart, hardworking, caring and knowledgeable!…
Olga G.
I had a truly wonderful experience working with HappyDog. From the very beginning, the team was professional, helpful, and prompt in guiding me through each step of the home loan process…
Jenny U.
If I could give Marci and Tori 10 stars I would! They were so friendly and easy to talk to. You can tell they enjoy helping people and that’s what makes them so good at their job!
RyAnn G.
Mike McKee, excellent service. His patience helped me to walk through the homebuying process with ease. He was available whenever I contacted him…
Althea O.
Great experience overall! Jason always kept us up to date and communicated regularly and is very good about replying quickly to questions.
AD A.
OMG!!! Mike Mckee is phenomenal…I worked with him for almost 2yrs..I had lots of issues prior to opening and he continued to reach out to me and stay in contact…
Valerie S.
Conventional loans work for most borrowers. Here’s what you should know.
As little as 3%. You don’t need 20% down to buy a home. If you put down less than 20%, you’ll pay private mortgage insurance (PMI) until you’ve paid off 20% of the mortgage. Once you hit 20% equity, that PMI goes away, usually within 5 to 10 years depending on your loan.
A minimum of 620. Conventional loans reward borrowers with better credit, offering lower interest rates as your score goes up. If you’re below 620, FHA or other programs might work better.
Conventional has a higher credit requirement (620 vs. 580 for FHA) but offers lower rates and the option to avoid mortgage insurance at 20% down. FHA has more lenient credit but charges mortgage insurance regardless of down payment. We’ll show you both and explain the trade-offs.
You don’t necessarily need to refinance. Many conventional loans allow automatic PMI removal once you reach 20% equity. Check your loan docs or ask us, we can walk through your options.
Typically 14 to 21 days from contract to keys. Our streamlined process and dedicated loan officer keep things moving without cutting corners on transparency.
Ready to explore your options? Get a free, personalized rate quote. Takes less than a minute and tells you exactly where you stand. ChooseHappy